IEA Accelerates Release of 20 Million Barrels — NRG-IA
Geopolitică & Energie Author: Ioana BuzoaicaThe IEA is accelerating the release of over 20M barrels of diesel from emergency reserves amid a global crisis hitting transport, industry, and prices.
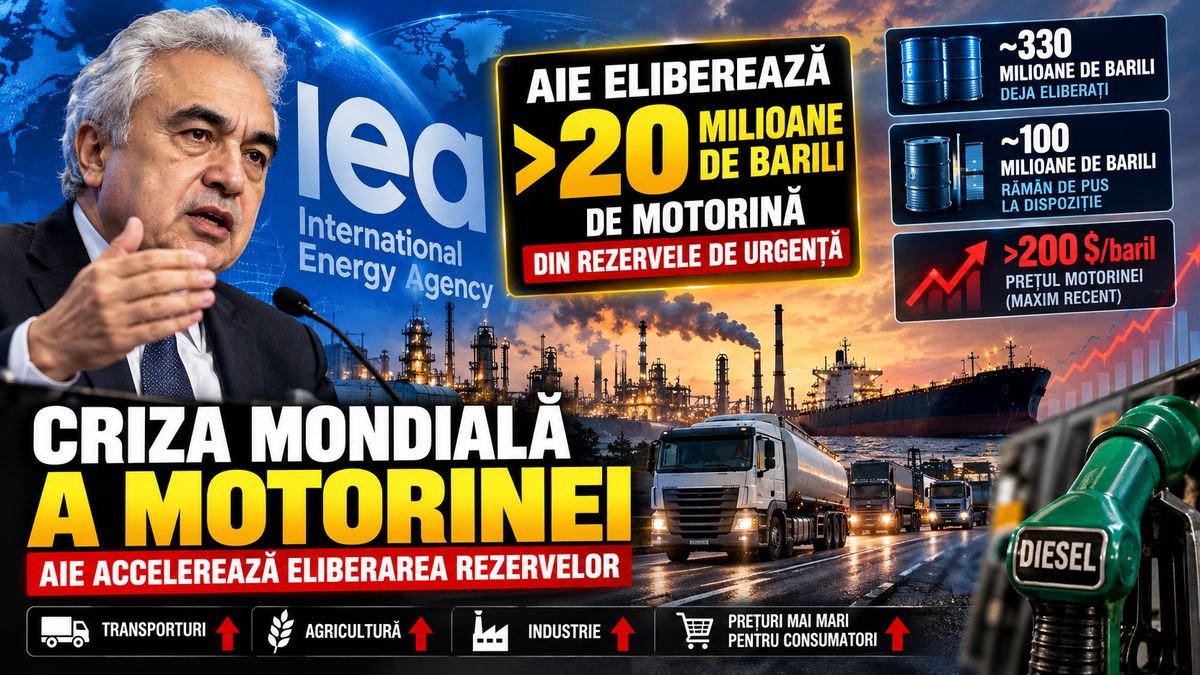
On October 15, 2026, the International Energy Agency (IEA) decided to accelerate the release of over 20 million barrels of diesel from emergency reserves in an effort to curb pressure on a global market hit by output cuts and fuel export declines. The decision follows previous actions by member states that have already made around 330 million barrels of crude oil and petroleum products available as part of a collective intervention launched in March in response to the Strait of Hormuz crisis. The IEA Governing Board agreed to expedite the delivery of remaining volumes from existing commitments, estimated at roughly 100 million barrels, with priority given to diesel. Several member states have already exceeded their initial pledges, while others plan to do the same, bringing the total intervention above the initial 400-million-barrel commitment. The more than 20 million barrels of diesel represent volumes whose release will be fast-tracked under the current program. The decision highlights the severity of a crisis that extends far beyond the crude oil market. While Middle Eastern crude flows have recovered a significant portion of lost volumes, shipments of refined products remain severely constrained. Diesel—vital for freight transport, agriculture, and numerous industrial operations—has become one of the most vulnerable segments of global energy supply. According to the IEA, persistent supply shortfalls and drawing down of stocks could keep market conditions tight well into 2027. Global diesel exports fell by 700,000 barrels per day The extent of the imbalance is documented in the IEA's monthly report published on October 14. In September 2026, seaborne global exports of diesel and gasoil dropped to approximately 4.7 million barrels per day (bpd), nearly 700,000 bpd below levels recorded in the same month of 2025. The decline was primarily driven by disruptions in the Middle East and deteriorating Russian refining capacity following Ukrainian attacks. Combined net exports of diesel and gasoil from Russia and the Middle East contracted by about 1.3 million bpd compared to September 2025—a decline of over 60%. Increased shipments from the United States and China, estimated at around 610,000 bpd, partially offset the losses, but global fuel availability continued to deteriorate. The two affected regions are major suppliers to international refined product markets, and replacing lost volumes requires alternative refining capacity and shipping routes. A key divergence has emerged between the recovery of crude oil exports and that of refined fuels. In September, Gulf producers exported approximately 13.9 million barrels of crude oil per day, recovering to over 75% of pre-war levels. By contrast, Middle Eastern refined product exports reached just 1.9 million bpd, compared to 4.7 million bpd before the conflict. The significantly slower recovery of refined exports explains why diesel availability remains constrained even as more crude oil circulates in the market. The situation is compounded by developments in Russia. Ukrainian strikes on refineries have impaired the ability of several facilities to process crude and produce fuels for domestic consumption and export. Furthermore, the loss of crude flows through the Strait of Hormuz reduced throughput at Asian refineries reliant on Gulf supplies. Consequently, disruptions in two major energy regions are simultaneously impacting global diesel production and international trade. Diesel prices topped $200 per barrel, transmitting pressure across the economy Dwindling fuel supplies triggered extraordinary price surges. According to the IEA, wholesale diesel prices surpassed $200 per barrel in Singapore in September, reaching record highs near $220 per barrel in Europe and the United States. Although benchmark prices later backed off from these extreme highs, they remained nearly double pre-crisis levels and crude oil prices across key indicators tracked by the agency. The diesel rally reflects structural challenges distinct from crude oil price trends. Crude oil must be processed in refineries before it can power engines, meaning final fuel availability depends on plant capacity, feedstock quality, and efficient supply chain operations. When diesel demand outpaces available supply, the crack spread—the difference between refined product prices and crude oil—can widen dramatically. This gap, known in the oil industry as the refining margin for the product, expanded dramatically during the crisis. At the same time, record freight rates and higher crude costs began squeezing margins at European and Asian refineries. The IEA warns that further margin erosion could prompt less efficient plants to reduce run rates, worsening the fuel deficit. The fallout extends far beyond the energy sector. Diesel powers freight trucks, farm machinery, construction equipment, and numerous industrial processes. Higher diesel prices raise operating expenses for businesses and can quickly…
Ioana Buzoaica — Independent Editorial Board
The NRG-IA newsroom continuously monitors Romanian energy markets, ANRE regulatory decisions, and national grid telemetry (SEN/SNT). We deliver independent intelligence anchored exclusively in official primary data.
Editorial Charter, Ethics & Verification Methodology →