Diesel Crisis Could Last Into 2027: IEA Warning & Impact — NRG-IA
Piața de Energie Author: Ioana BuzoaicaThe IEA warns global diesel supplies will remain under pressure well into 2027 despite crude recovery, impacting transport, industry, and consumer prices.
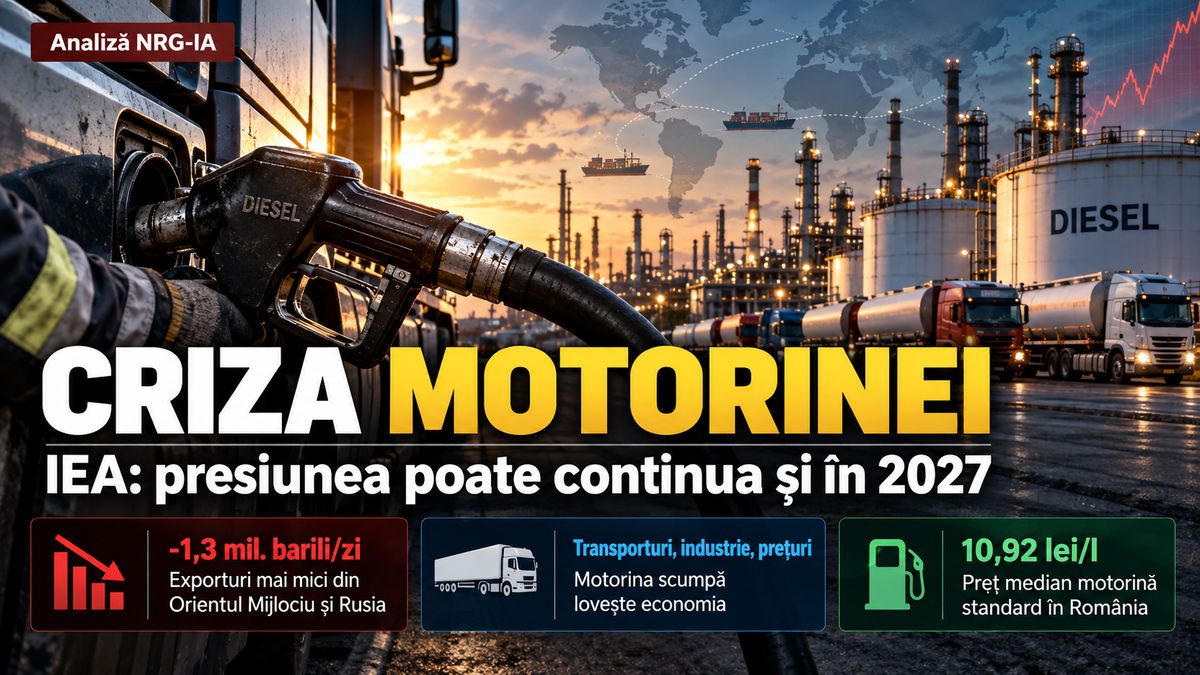
The global diesel crisis threatens to extend well into 2027, with ripple effects on transport, industry, and inflation, warns the International Energy Agency (IEA) in its oil market report published on October 14, 2026. Although crude oil production is beginning to recover following disruptions caused by the conflict in the Middle East, diesel supply remains insufficient, and depleted inventories are rebuilding at a much slower pace. In September, combined net exports of diesel and gasoil from the Middle East and Russia dropped to approximately 820,000 barrels per day, 1.3 million barrels per day below levels recorded in the same month of 2025. This fall exceeds 60% and underscores the extent of disruptions in two key regions for global refined petroleum product supplies. Producers in other regions partially offset these losses, keeping the net decline in global diesel and gasoil exports to around 700,000 barrels per day. Even so, available volumes remained insufficient to prevent inventory draws ahead of the cold season, when demand for heating, transport, and economic activities places additional strain on the market. Crude returns to the market, but diesel remains insufficient One of the most significant developments in the current energy crisis is the disconnect between the recovery of crude oil exports and the rebound in refined product shipments. In September, crude exports from Gulf producers rose by 4.4 million barrels per day to 13.9 million barrels per day, reaching over 75% of pre-war levels. At the same time, shipments of refined petroleum products from the Middle East stood at just 1.9 million barrels per day, compared to roughly 4.7 million barrels per day before the conflict. Thus, while the region managed to recover a major share of its crude exports, fuel and other refined product exports stayed at less than half of pre-crisis levels. This mismatch has direct consequences on prices. Crude oil must be transported, processed in refineries, and converted into end-products that meet market demand. Available refining capacity, the slate of crude processed, and logistics for moving finished fuels to importing regions dictate how much diesel actually reaches the market. The Middle East conflict dampened activity at several refineries and disrupted maritime shipping routes. In Asia, reduced crude flows through the Strait of Hormuz hit refinery runs. Russia, meanwhile, faces reduced diesel production and exports due to refinery damage caused by Ukrainian drone strikes. Additional constraints have exacerbated the issue. Strong demand for jet fuel prompted some refiners to favor kerosene production over diesel. Furthermore, supply bottlenecks for specific crude grades reduced the efficiency of refineries configured to process them. Under these conditions, higher global crude production does not automatically translate into an equivalent surge in diesel availability for transport operators, industry, and consumers. Diesel hits record prices while inventories continue to fall In September, wholesale diesel prices surpassed $200 per barrel in Singapore and reached record highs of around $220 per barrel in Europe and the United States. Although prices have since eased from those peaks, quotes remain nearly double pre-crisis levels and twice the price of crude oil. These elevated prices boosted margins for certain refiners by widening the spread between produced diesel and input crude. However, record shipping costs and pricier delivered crude eroded profitability at several European and Asian refiners. In Europe, the diesel-to-crude spread narrowed from around $100 per barrel to nearly $60 per barrel by early October. This cost pressure risks capping refiners' ability to boost output precisely when the market requires additional fuel volumes. Inventories reflect the accumulated imbalance. In July, OECD diesel and gasoil stocks fell to roughly 565 million barrels, 5% below pre-conflict levels. Globally, observed oil inventories—including crude and refined products—were 509 million barrels lower at the end of September than at the end of February 2026. The IEA projects global refinery runs to rise from a seasonal low of 81.3 million barrels per day in October to 84.6 million barrels per day by the end of the year. This recovery could push the diesel market into a seasonal surplus in the first quarter of 2027; however, this surplus would be insufficient to replenish the inventories lost in 2026. According to the agency, a more substantial inventory build—beyond normal seasonal swings—is unlikely before the second half of 2027. The outlook hinges critically on the recovery of Middle Eastern refined product exports. Transport and industry pass higher diesel costs to consumers Diesel is one of the fuels most directly linked to broader economic activity. Freight trucks, agricultural machinery, construction equipment, and numerous industrial facilities rely on a steady supply of diesel fuel. Unlike other refined…
Ioana Buzoaica — Independent Editorial Board
The NRG-IA newsroom continuously monitors Romanian energy markets, ANRE regulatory decisions, and national grid telemetry (SEN/SNT). We deliver independent intelligence anchored exclusively in official primary data.
Editorial Charter, Ethics & Verification Methodology →