Diesel Hits Record Highs in Europe: Low Stocks & Supply Risks — NRG-IA
Piața de Energie Author: Ioana BuzoaicaEurope pays record prices for diesel as issues shift to refining and stocks. Romanian diesel nears 11 lei/liter, driven by costly regional imports.
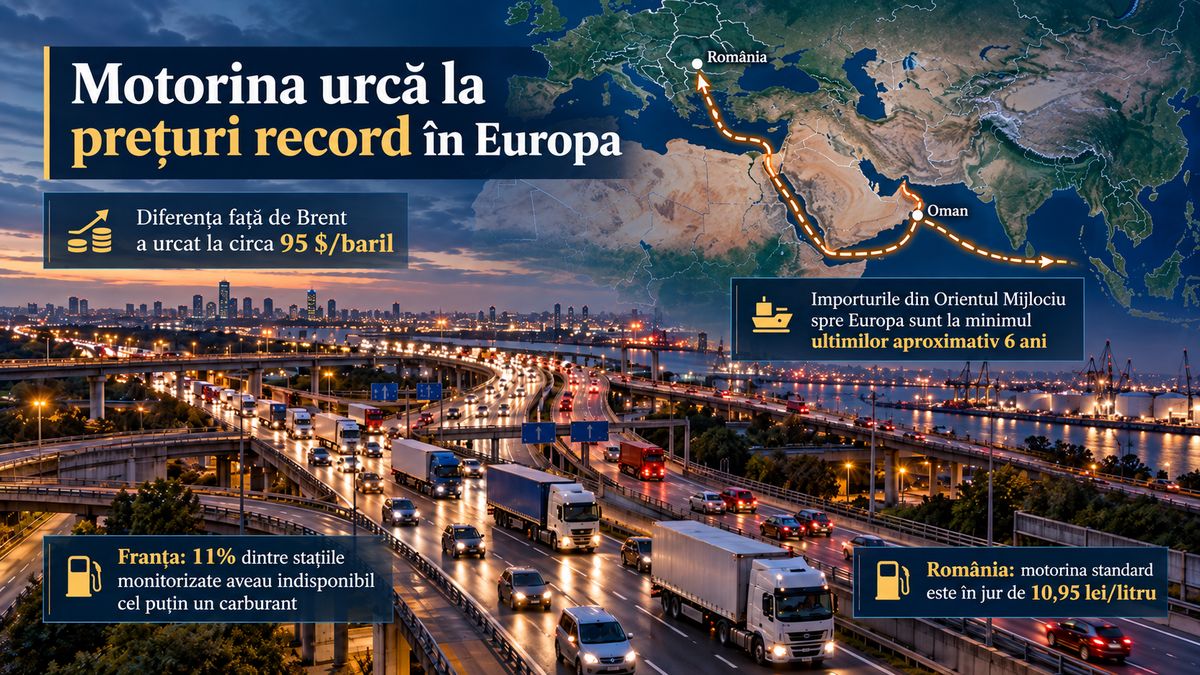
The fuel market has become one of the most strained energy markets this autumn. While Brent has returned toward the $100/barrel threshold, European diesel has continued to grow more expensive, and the price spread between the refined product and crude oil has climbed to approximately $95/barrel. This spread indicates that the issue is no longer just the price of crude. Europe must source diesel in a market where Middle Eastern exports have plummeted, Russia has cut its shipments, inventories are low, and many refineries are already operating close to their limits. The first local availability issues have emerged in France, while in Romania, the impact is currently felt primarily through prices. Diesel Prices Rise Even as Crude Oil Falls On September 23, the spread between European diesel and Brent crude reached a record high of approximately $95/barrel. In the physical market, tensions had already surfaced at the beginning of the month. S&P Global assessed the diesel margin in the Amsterdam–Rotterdam–Antwerp (ARA) hub—the main European trading center for petroleum products—at around $98/barrel. Finished product prices climbed in tandem. Ultra-low sulfur diesel delivered to Northwest Europe was valued at over $1,640/tonne in mid-September, while in the Mediterranean region, it surpassed $1,660/tonne. These values do not represent automatic refinery profits; rather, they show how much the value of diesel has surged relative to the raw material from which it is produced. Consequently, cheaper crude oil does not automatically guarantee cheaper diesel. If refineries cannot produce enough, inventories remain low, and imports are difficult to replace, upward pressure on prices will persist. The Crisis Has Shifted to Refineries and Finished Products The current situation differs from a classic crude supply crisis. There is oil on the market, but diesel must be refined. Trucks, agricultural machinery, diesel cars, and a large portion of industrial equipment do not consume crude oil, but rather the product resulting from its processing. This is where one of the system's main bottlenecks lies. Many refineries outside the affected areas are already operating at high utilization rates. In the United States, refinery utilization reached its highest level in eight years at the end of August. Record margins incentivize refineries to produce more diesel, but available spare capacity is limited. Consequently, an outage or a major shutdown at a key facility can have a much larger impact in a market with low inventories. The Middle East Delivers Far Less Diesel to Europe Until recently, the Middle East was one of Europe's primary sources of diesel. In 2025, the region accounted for approximately 41% of European imports. However, between March and August 2026, regional diesel exports fell to around 800,000 barrels per day (bpd), roughly half the level of the previous year. In September, direct flows to Europe dropped even further, to approximately 110,000 bpd from 191,000 bpd in August. This is the lowest level in about six years. Oman has emerged as one of the regional sources capable of maintaining more stable exports, as the ports of Sohar and Duqm are located outside the Strait of Hormuz. For Romania, there is a direct link: S&P Global data points to Romania as the primary European recipient of Middle Eastern diesel volumes reaching the continent in September. Romanian supply is thus directly connected to one of the markets where available volumes have dropped most sharply. Russia Removes Another Major Supplier from the Market A second shock comes from Russia, one of the world's largest diesel exporters. Attacks on Russian refineries have disrupted processing, and Moscow introduced a diesel export ban in July, which has been extended until the end of October. While the European Union no longer imports direct Russian diesel in pre-sanction volumes, the withdrawal of Russian product impacts the global market. Countries that previously bought from Russia must replace those volumes from other sources, thereby competing with Europe for the same cargoes. Available supply is shrinking while the number of buyers is growing. European Inventories Are Low The main European petroleum product hub, Amsterdam–Rotterdam–Antwerp, entered September with unusually low diesel inventories for this time of year. In July, levels were approximately 16% below the five-year average. Additional imports, particularly from the United States, allowed for a partial recovery in the first half of September, when diesel and gasoil inventories rebounded toward 1.65–1.68 million tonnes. Europe still has product available, but it is attracting it at very high prices. As nearby sources dwindle, traders must haul diesel from greater distances, and Europe must offer a price attractive enough to divert those cargoes to its terminals. France Already Faces Local Fuel Station Issues In France, the strain has reached retail filling stations. Government data from…