US Diesel Hits Record $6.40/Gal: Low Stocks, Max Refining — NRG-IA
Piața de Energie Author: Ioana BuzoaicaUS diesel hit a record $6.3956/gal, while the EIA expects stocks to fall below 100M barrels. America enters autumn with a tight safety margin.
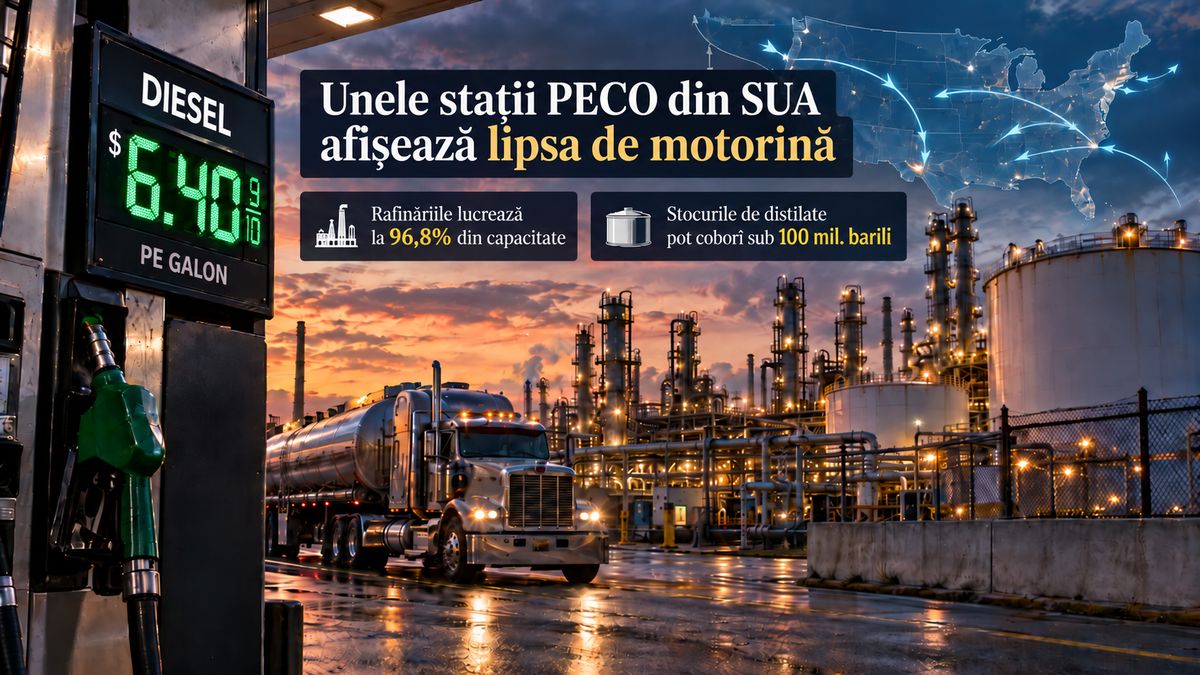
On September 17, US diesel reached $6.3956 per gallon , the highest level in the history of the AAA data series. A year ago, it cost $3.7075, representing an increase of approximately 72.5% . In California, the average climbed to a record $8.3496/gallon . At the same time, photos of gas stations displaying "OUT" of diesel or blanked-out prices circulated widely on social media, fueling rumors that the United States was running out of diesel. While local incidents do occur, national data indicates a different situation: the US still has over 100 million barrels of distillates in stock, and inventories rose slightly in the latest reported week. The real issue is that their level remains low, leaving the system with increasingly little room for another shock. The record price is real, even if the national shortage is not At $6.3956/gallon, US diesel costs the equivalent of approximately $1.69 per liter , before currency conversion. In California, the average exceeds $2.20 per liter. This surge is significant because diesel is not just a fuel for a specific segment of drivers. It powers a major portion of road freight, agricultural machinery, construction, rail transport, and numerous industrial activities. Reuters noted earlier this month that the average crossing above $6/gallon amplifies pressure on transportation, agriculture, and real economy costs. Consequently, the impact of diesel prices extends far beyond the pump. A transport company paying more for each trip passes a portion of the cost onto freight rates, which subsequently feed into the prices of food, materials, parts, and consumer goods. Inventories rose in a week, but remain well below the comfort zone For September 11, the EIA reported 107.859 million barrels of distillates in US inventories, up from 106.274 million a week earlier. Thus, inventories are not depleting linearly from week to week. The pressure stems from structural levels. The EIA's Short-Term Energy Outlook estimates that distillate stocks will fall below 100 million barrels in September and remain below the lower bound of the five-year range until the end of 2026 and for much of 2027. The East Coast has already provided a warning. Regional inventories fell to 19.318 million barrels on August 28 , before recovering to 21.583 million on September 11. While the recent recovery eases immediate pressure, levels remain low ahead of the cold season, when distillates are also used for heating in the US Northeast. Refineries are producing near system limits The United States is not facing a general shortage of crude oil. Domestic production was approximately 13.94 million barrels per day in the week ending September 11. The more severe constraint lies in refining that crude into sufficient products within a highly tight global market. US refineries reached 98% utilization at the end of August and were still operating at 96.8% on September 11. In other words, there is relatively little room for rapid additional production increases if demand or exports spike. This is why crude oil and diesel prices can diverge. Crude may sit in storage or continue to be produced, but diesel must be refined, transported, and distributed before reaching the pump. Washington relaxes logistics rules for 90 days On September 16, the Department of Transportation granted a temporary 90-day waiver for gasoline and diesel haulers. Eligible drivers can operate up to 16 hours within a 24-hour window, subject to rest and safety requirements. The administration presents the measure as a way to prevent logistical delays from turning into availability and cost issues. The Department of Transportation explicitly points to freight transport and agriculture among the sectors protected by this flexibility. The waiver is not an official declaration of a shortage. However, it is a signal that authorities consider fuel distribution tight enough to temporarily expand the system's logistical capacity. The shock does not originate in America Most of the tension originates in the global market. The Strait of Hormuz has produced one of the largest recent energy shocks. McKinsey estimates that, at the peak of the 2026 disruption, restrictions in the strait affected approximately 14% of the combined global oil and gas supply —a share more than double the relative peak impact of the 1970s oil shocks. The market absorbed part of the shock through inventories, alternative routes, and demand destruction, but refined products have remained much harder to replace than crude oil. The second pressure point is Russia. Attacks on refineries have reduced output at major facilities, and Reuters reported on September 15 that half of the key Russian diesel-producing refineries analyzed had sharply reduced activity or shut down. These six refineries accounted for roughly half of Russian diesel production. Net exports of diesel and gasoil from Russia and the Gulf states are approximately 1.6 million barrels per day below February levels , according…