US Ships 6.89M Tonnes LNG to Europe; EU Storage at 74.6% — NRG-IA
Gaze Naturale Author: Ioana BuzoaicaUS LNG shipments to Europe surged by nearly 1 million tonnes in October 2026. As storage remains unusually low, Europe grows increasingly reliant on US supplies.
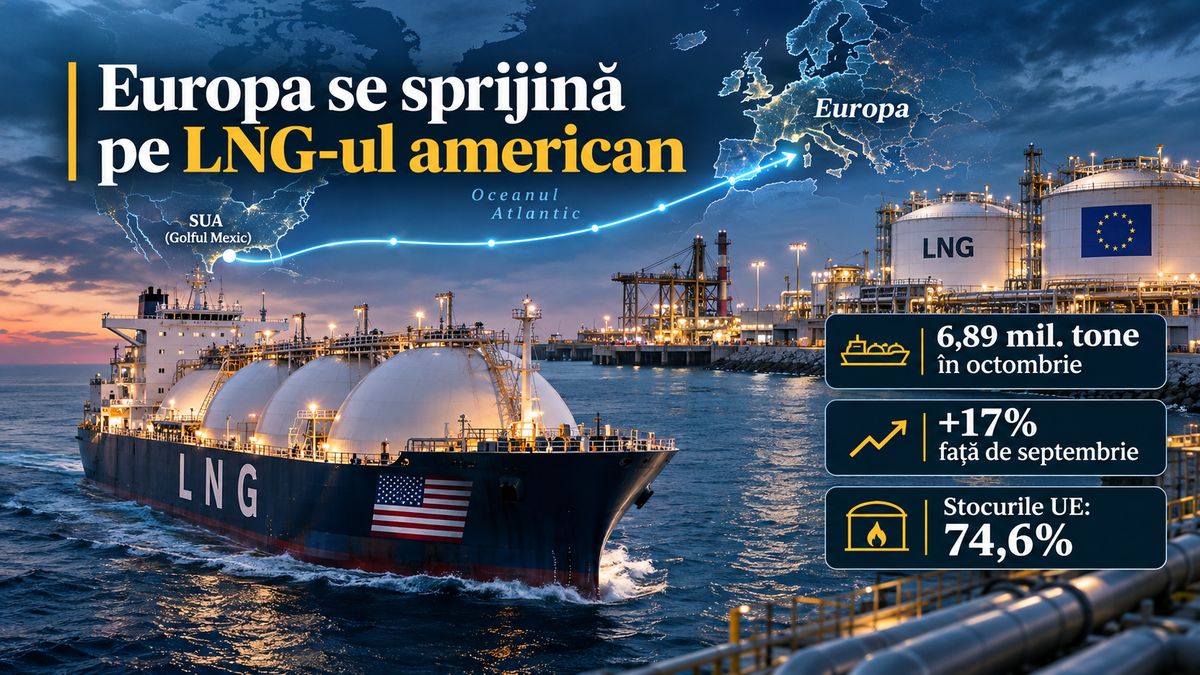
The United States shipped 6.89 million tonnes of liquefied natural gas (LNG) to Europe in October 2026, nearly one million tonnes more than in September. The 16.6% single-month surge, highlighted by LSEG vessel-tracking data analyzed by Reuters, brought total US exports close to a new record high. October marked the second-highest month on record for US LNG exports. The surge in shipments underscores a profound transformation in European energy supply. The European Union enters the 2026–2027 heating season with gas storage facilities filled to just 74.6%, while Qatari deliveries are impaired by the conflict in the Middle East and European and Asian buyers compete for available global volumes. The scale of this shift is confirmed by the European Union Agency for the Cooperation of Energy Regulators (ACER). According to a report published in late October, US LNG already accounts for around 30% of total EU gas supply. In just a few years, the United States has become a central pillar of European energy security, with the availability of US cargoes increasingly dictating market balance. Europe Receives Nearly One Million Additional Tonnes of US LNG in a Single Month LSEG data shows that US LNG shipments bound for Europe rose from 5.91 million tonnes in September to 6.89 million tonnes in October. The 980,000-tonne increase represents a nearly 17% jump, highlighting a push to bolster supplies ahead of the peak space-heating demand period. Over the same period, US exports to Asia dipped slightly from 2.84 to 2.73 million tonnes. Consequently, Europe drew over two and a half times the volume destined for the Asian market, according to tracked shipments in the LSEG data. Deliveries to Egypt held steady at around 680,000 tonnes, while shipments to Latin America rose from 530,000 to 680,000 tonnes. An additional 590,000 tonnes left US terminals without a confirmed final destination, with vessels still uncommitted at sea at the time of the assessment. These shipments illustrate the commercial flexibility of the LNG market, where uncommitted cargoes can adjust their destination based on real-time demand, prices, and contractual terms. The expansion of exports is supported by additional liquefaction capacity coming online in the United States. The US Energy Information Administration (EIA) reports that LNG exports grew by 23% in the first half of 2026 compared to the same period last year, averaging 17.4 billion cubic feet of gas per day. Projects such as Plaquemines LNG, Corpus Christi Stage 3, and Golden Pass are expanding US export capabilities. At the Golden Pass terminal in Texas, co-owned by QatarEnergy and ExxonMobil, cargo shipments doubled to four in October compared to the previous month. The ongoing expansion of US export terminals allows the United States to meet high global demand at a time when LNG availability has become a strategic concern for many economies. European Storage Stands at 74.6%, with Germany Starting Winter at Just 61% The rising reliance on US LNG coincides with a tight European storage outlook. According to Gas Infrastructure Europe data, by early November, EU storage facilities held roughly 844 TWh of natural gas, representing 74.56% of total working storage capacity. This level is noticeably below seasonal norms for this time of year. Divergence among member states is significant. Germany, Europe's largest economy, saw its storage levels at just 61.05%, whereas France stood at 86.4%, Italy at around 91%, and Poland above 99%. Romania was in a relatively comfortable position, with storage at 88.62%, equivalent to roughly 30 TWh of gas. Underground storage plays a critical role in balancing the European market during winter. According to the European Commission, storage typically covers 25–30% of winter gas consumption, helping absorb demand spikes and potential supply disruptions. The lower the available volumes at the start of winter, the greater the reliance on spot and ongoing imports. ACER warns that Europe enters the heating season with reserves below the nine-year average. This reflects lower stock levels remaining at the end of the previous winter as well as a sluggish summer injection season, driven by high wholesale prices and weak commercial incentives for storage injection. At the same time, European storage regulations currently provide increased flexibility. The general 90% fill target can be achieved between October 1 and December 1, and member states can obtain derogations under tight market conditions. Nevertheless, current inventory levels translate into a thinner operational buffer for the winter, regardless of regulatory leniency. Qatari Deliveries Drop as Europe and Asia Compete for Available Gas A key driver of altered trade flows is the disruption to Middle Eastern global LNG supply. Conflict erupting in early 2026 impaired transit through the Strait of Hormuz, a key choke point for a substantial share of the region's energy exports. The EIA notes that disruptions…
Ioana Buzoaica — Independent Editorial Board
The NRG-IA newsroom continuously monitors Romanian energy markets, ANRE regulatory decisions, and national grid telemetry (SEN/SNT). We deliver independent intelligence anchored exclusively in official primary data.
Editorial Charter, Ethics & Verification Methodology →